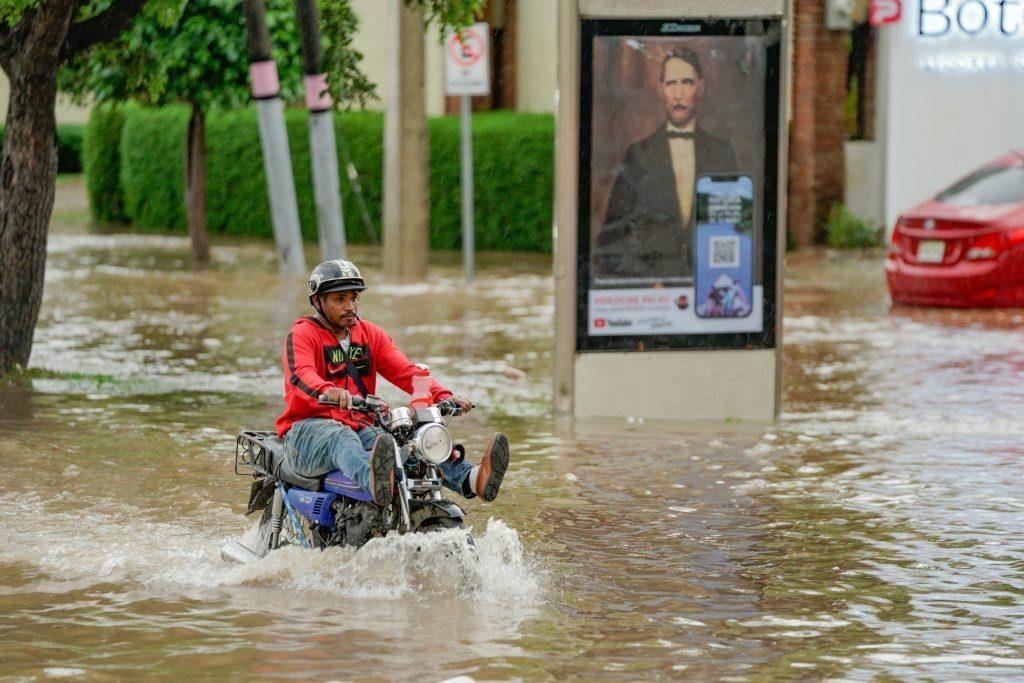
When floodwaters rise or hurricane winds howl, your first thought is your pet’s safety—not paperwork. But here’s the painful truth: without pet storm insurance emergency coverage, a single natural disaster can drain your savings faster than a flash flood. I learned this the hard way during Hurricane Ida when my dog Rex swallowed contaminated water while evacuating. The vet bill? Over $3,200. Our standard pet insurance didn’t cover storm-related emergencies. That mistake cost me dearly—and it’s why I’m sharing exactly how to protect your furry family before disaster strikes.
Table of Contents
- Why Standard Pet Insurance Isn’t Enough
- Your 5-Step Emergency Preparedness Plan
- 7 Best Practices for Storm Season
- Real Stories, Real Savings
- Frequently Asked Questions
Key Takeaways
- Standard pet insurance often excludes natural disaster injuries—verify your policy’s “perils” clause.
- Only specialized pet storm insurance emergency plans cover evacuation vet visits, contaminated water ingestion, and storm-induced anxiety treatments.
- Keep digital copies of vaccination records and policy details in cloud storage—physical papers get soaked.
- The average emergency vet visit during floods costs $1,800–$4,500 (AVMA data).
- Update your plan annually before storm season—most insurers lock rates until renewal.
Why Standard Pet Insurance Isn’t Enough
Most pet owners assume their insurance covers “all emergencies.” Not true. Traditional policies exclude “acts of God”—floods, hurricanes, wildfires—unless you’ve added specific riders. According to the American Veterinary Medical Association (AVMA), 68% of storm-related pet claims are denied due to exclusion clauses. During Hurricane Harvey, Houston vets reported a 300% spike in dehydration and wound cases from debris—but only pets with pet storm insurance emergency coverage got reimbursed.
Your 5-Step Emergency Preparedness Plan
1. Audit Your Current Policy
Call your insurer and ask: “Does my plan cover injuries from federally declared disasters?” If they hesitate, you need an upgrade. Look for keywords like “natural peril endorsement” or “evacuation expense coverage.”
2. Compare Specialized Providers
Companies like Trupanion and Nationwide offer storm add-ons. Focus on three metrics: deductible (aim for ≤$250), reimbursement rate (80%+), and waiting period (≤14 days). Avoid plans requiring pre-approval during active storms—that’s useless mid-hurricane.
3. Build a Digital Go-Bag
Store vaccination records, microchip number, and policy PDFs in Google Drive. Include a printed emergency contact card taped to your carrier. Tip: Add a photo of your pet’s paw print—it speeds up ID if collars detach.
4. Pre-Identify Vet Clinics
Map 3+ 24/7 ER vets along your evacuation route. Save their numbers in your phone’s ICE (In Case of Emergency) profile. Pro tip: Bookmark the ASPCA’s national shelter database (aspca.org/pet-care/disaster-preparedness)—it lists pet-friendly hotels too.
5. Test-Run Evacuations
Practice loading carriers into your car monthly. Reward calm behavior with treats. My terrier used to panic—now she jumps in willingly because “storm drill = bacon time.”
7 Best Practices for Storm Season
- Never skip the microchip update. After relocating post-Katrina, 41% of pets couldn’t be reunited due to outdated chips (CDC data).
- Avoid “bargain” insurers with no BBB accreditation—they often deny claims citing “pre-existing storm exposure.”
- Keep electrolyte paste (like Pedialyte) in your kit—vets recommend it for dehydration.
- Photograph your pet weekly during storm season; fresh images help shelters identify them.
- Link your policy to automatic payments—lapsed coverage voids all disaster protections.
- Share your emergency plan with neighbors (include their contact info in your go-bag).
- Review FEMA’s pet guidelines (ready.gov/pets) annually—they update evacuation protocols yearly.
Real Stories, Real Savings
Last year, Florida resident Maria evacuated during Hurricane Ian with her diabetic cat Luna. At an emergency clinic, Luna needed insulin stabilization after stress-induced hyperglycemia—costing $2,900. Because Maria had added a pet storm insurance emergency rider to her Lemonade policy, she was reimbursed 90% within 72 hours. Contrast this with Ben in Louisiana, whose standard insurer denied his claim for his dog’s floodwater leptospirosis treatment, calling it an “excluded environmental hazard.” His out-of-pocket? $4,100. These stories prove that specialized coverage isn’t optional—it’s essential.
Frequently Asked Questions
Does pet storm insurance cover boarding costs during evacuations?
Yes—if your policy includes “temporary boarding” under emergency provisions. Verify this before purchasing.
Can I buy coverage after a storm warning is issued?
No. Insurers impose 10–30 day waiting periods once a named storm forms. Buy before June 1 (Atlantic hurricane season start).
Are pre-existing conditions excluded from storm claims?
Only if related. Example: Arthritis isn’t excluded, but if storm stress worsens it, treatment may be covered.
How fast do reimbursements process post-disaster?
Reputable providers (e.g., Healthy Paws) pay within 3–5 business days. Always submit digital claims immediately.
Does this cover wildlife encounters during floods?
Yes—snake bites, alligator scrapes, or raccoon fights during displacement are typically included.
What’s the biggest mistake pet owners make?
Assuming homeowner’s insurance covers pet medical bills. It doesn’t. Only standalone pet storm insurance emergency plans do. Also, never rely on crowdsourced “rescue” groups—they lack medical resources.
Don’t wait for dark clouds to read fine print. Update your coverage today, then contact us with questions—we’ve helped thousands navigate storm prep (learn more on our About Us page). And remember: your data stays secure per our Privacy Policy. When thunder roars, go indoors—and know your pet’s protected.
Fur-ever safe, not sorry.